Coffee first
An hour or so on where you need to be, what you want to spend and what you can live without. Your life first, then the budget.
The right home is more than good light and a great kitchen. It's the street, the numbers and the school run. I'll tell you what's wrong with a place before you fall for it.
You don't need to love every house. You need one that works for your life long after move-in, and someone honest enough to say when a place isn't it.
You can love the house and still ask hard questions.
An hour or so on where you need to be, what you want to spend and what you can live without. Your life first, then the budget.
Pre-approval before the first showing, lenders I trust, and closing costs mapped so nothing surprises you.
Must-haves, deal-breakers and the absolutely-nots: street, schools, commute, home type.
In person or on video with my running commentary. I point out the cracks, and look past what's online.
We write a practice offer before you find the one, so offer night is never your first time. Then recent sales, what the seller cares about, firm or conditional.
Inspection, financing, lawyer, status certificate. I track every deadline and get you back in before closing.
My trades list, a yearly value check, and a text back whenever you need one.
Max refund for eligible first-time buyers. Neither you nor your spouse can have owned a home anywhere.
On top of the Ontario refund, for eligible first-time buyers in the city.
$8,000 a year, $40,000 lifetime. Deductible going in, tax-free coming out for a first home.
Borrow from your RRSP for a first home. You can use it together with your FHSA.
Figures as of October 2026. Eligibility rules apply and programs change; your lawyer and lender confirm what you qualify for.
Play with the price, down payment and rate to see your monthly payment, then check both land transfer taxes. Toronto buyers pay two.
Estimates only, as of October 2026. Mortgage uses Canadian semi-annual compounding; insurance applies under 20% down on homes under $1.5M. Your lender, lawyer and the stress test have the final word.
Going firm can win a house. It should never be a guess.
Toronto offers have their own rules of play. Some sellers hold an offer date, some take offers any time, and some buyers try to jump the line with a bully offer. Each calls for a different move.
I'm a Certified Negotiation Expert, and this is where it matters. We decide ahead of time when to go firm, when to keep a condition, how big the deposit should be and where your walk-away number is. Then I negotiate like it's my money.
What you get from me: straight answers, fast updates, and the nerve to tell you to pass on a house when a better one is coming. Plus early word on homes other agents are about to list.
What I ask from you: honest, regular back-and-forth. Treat the search like a part-time job for a few months. Tell me the moment something feels off, and we'll fix it.
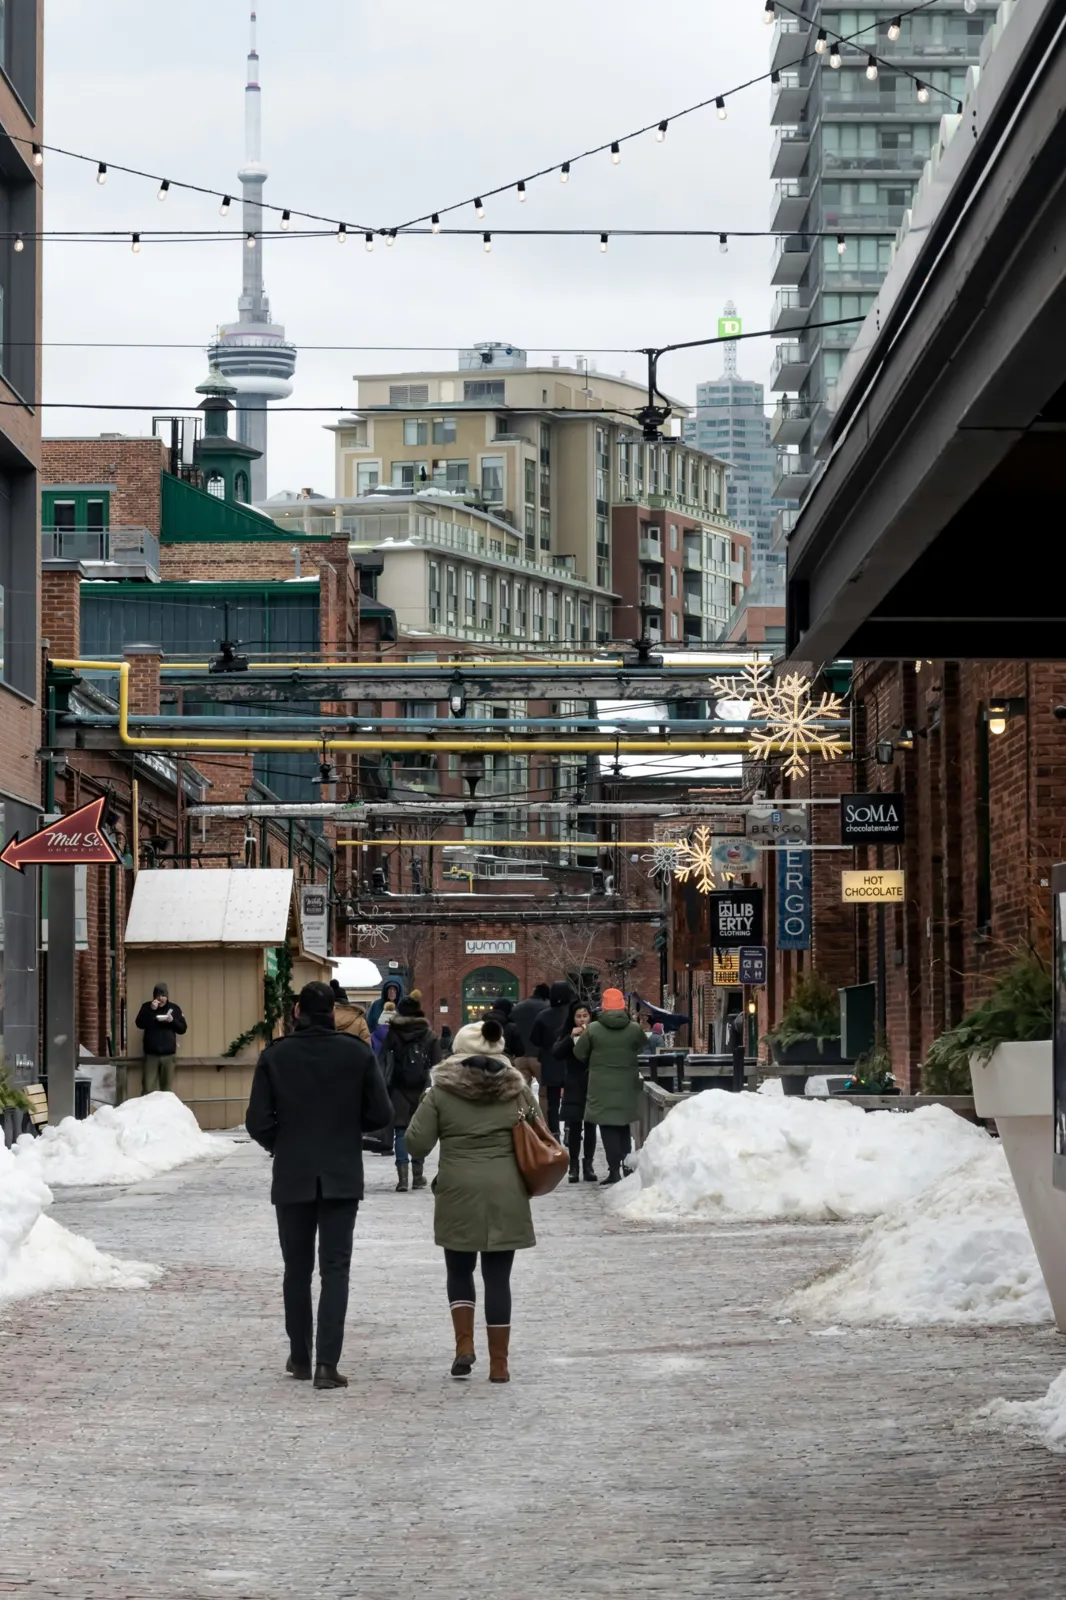
Pick the life, then the house. Toronto is a hundred small towns. Commute, walkability, schools and green space shape your days more than square footage, so we match the neighbourhood first.
Not sure yet? Rent for six to twelve months, learn the city, then buy with confidence. Already sure? We can shortlist and tour on video before you land.
Sell first and you know exactly what you can spend. Buy first and you lock in the place you love, but you may need bridge financing and a firm deadline to sell.
Most of the time, I line up both closings within days of each other, so you only move once.
Not sure what you're looking for?
Let's narrow down the right area for you.
Before we start, we sign a buyer representation agreement that spells it out. In most purchases the buyer's agent is paid from the commission on the sale, and I walk you through every line before you sign.
5% on the first $500,000, 10% on the part between $500,000 and $1.5M, and 20% on homes $1.5M and up. Under 20% down, you pay mortgage insurance, usually added to the mortgage.
Your down payment plus closing costs, usually 1.5% to 4% of the price: land transfer tax (two of them in Toronto), legal fees, title insurance and adjustments. We build your real number in the first meeting.
Lenders qualify you at your mortgage rate plus 2%, or 5.25%, whichever is higher. It shrinks your budget a little, so get pre-approved before you fall for anything.
Spring and fall bring the most listings and the most competition. Winter is quieter, with more room to negotiate. Summer suits families moving between school years.
Yes. A qualifying FHSA withdrawal and a Home Buyers' Plan withdrawal can go toward the same purchase.
The condo corporation's file on the unit and building: reserve fund, lawsuits, special assessments. Up to $100, delivered within 10 days. Your lawyer should review it, usually as a condition.
Sometimes. Agents talk about upcoming listings before they go live, and I'm in those conversations. When something fits, you hear about it first.
Citizens and permanent residents buy like anyone else. Until January 1, 2027, federal rules stop most non-Canadians from buying homes here, with exceptions such as some work-permit holders. Eligible foreign buyers also pay Ontario's 25% speculation tax plus Toronto's 10%. We check your status first.
First place, the family home, more space, or just figuring out what's next. You don't need it all mapped out. Tell me what's on your mind and we'll start there.
Come behindthe scenes.
Open houses, new listings, neighbourhood finds and the odd round of golf.
Follow @davidspeedie Preview photos until the live feed is connected